1190 consumer brands in these ledgers have been sold outright or had their IP sold. Each one's owner is the buyer in its latest sale, across 831 owners. 469 sales have a logged close. The rest were announced, and count unless they publicly fell through, as 3 did.
- L'Oreal holds the most mapped brands, with 9.
- 39 brands changed hands again after an earlier sale.
Who counts as
the owner.
A brand's owner here is the buyer in its latest acquisition or IP purchase. A minority stake does not make an owner, so stakes are left out.
Most deals are logged when they are announced, and the close is often never reported. So an announced sale counts as done unless a public report says it fell through. The line under each brand says which: 469 closes logged, 721 announced. 3 announced sales fell through and are listed in their own section.
Where a brand was sold, then sold again, the later sale wins. 39 brands are in that position and are listed with both owners. 1 mapped brands also have a later sale rumoured to a different buyer, noted under the owner.
The DTC brand you bought last week probably isn't owned by the people who founded it. The deodorant, the skincare, the denim, the electrolyte packets: most of the names that feel independent sit inside a parent company, a licensing holdco, a private-equity platform, or an Amazon roll-up. This is the map of who owns what now, organized by owner so you can find a brand and trace it to the entity that actually controls it.
I built this the way I'd want it if I were doing diligence: named entities, specific brands, dated deals, and a source for every ownership claim. Where a 2026 transaction set the current ownership, the deal and its price are cited. For each deal, the primary source (the SEC filing, the parent company's investor-relations release, or the regulatory clearance) is treated as the origin, with trade press cited only as secondary confirmation. Where a brand has sat inside a portfolio for years, the owner's own brand list is the source. Nothing here is guessed. If a rumor is only a rumor, it's labeled as one.
One note on why this matters beyond trivia. I spent years at WIN Brands Group deciding which brands to fold into a house of brands and which to pass on, and the single most useful thing you can know about a competitor, an acquisition target, or your own brand is who sits above it. The owner sets the pricing discipline, the shared-services stack, the exit timeline, and the ceiling. So this is a reference first, but it's also a lens: once you can see the ownership structure, the whole market stops looking like a list of logos and starts looking like a set of portfolios with agendas.
This is the companion to two other pieces. If you want to know which acquirers are doing the buying in 2026, that map is organized by acquirer activity. If you want the strategy debate over whether a house of brands should operate or license what it owns, that one is about the model. This page is the named-entity reference: who owns which brand, and where to find it.
The holdcos that own
the name and license
the rest.
Three firms dominate the asset-light end: Authentic Brands Group, WHP Global, and Marquee Brands. They own trademarks and license the operations, which is why their portfolios read like a department-store directory and their retail-sales figures dwarf their headcount. If a legacy apparel or lifestyle brand got acquired and kept running under new management, one of these three is often the owner behind it.
Authentic Brands Group is the largest by a wide margin, with more than 50 brands and roughly $38B in annual system-wide retail sales, per its own corporate portfolio disclosure. It had a loud 2026: it took a majority stake in Guess at a valuation of about $1.4B in January, acquired the Lee denim IP for $750M plus a $250M earnout in May, and agreed to buy the Care Bears IP in June. It was also reported as a potential buyer circling Converse as Nike refocuses, which remains exploratory rather than done.
| Holdco | Notable brands / IP owned | 2026 moves |
|---|---|---|
Authentic Brands Group 50+ brands, ~$38B system-wide retail sales | Reebok, Champion, Guess, Nautica, Eddie Bauer, Brooks Brothers, Juicy Couture, Aeropostale, Quiksilver, Billabong, Volcom, Sperry, Hunter, Ted Baker, plus entertainment IP (Marilyn Monroe, Elvis, Muhammad Ali) | Majority of Guess (~$1.4B, Jan); Lee IP ($750M + $250M earnout, May); Care Bears IP (Jun); majority of the OVO (October's Very Own) IP, reported at 51%, with Vince Holding taking the operating business as core licensee (undisclosed, Aug 27); reportedly circling Converse |
WHP Global $8B+ retail sales worldwide | Toys R Us, Babies R Us, Vera Wang, Rag & Bone, G-Star RAW, Joe's Jeans, Express, Bonobos, Anne Klein, Isaac Mizrahi, Joseph Abboud, Lotto | Marc Jacobs from LVMH ($850M, May); 50% controlling stake in Lands' End ($300M, Jan) |
Marquee Brands ~$5B portfolio-wide retail sales | Martha Stewart, Laura Ashley, Sur La Table, BCBG / BCBGMAXAZRIA, Ben Sherman, Bruno Magli, Body Glove, Dakine, Totes Isotoner, Destination Maternity, Stance | Majority of Roberto Cavalli, with DAMAC Group (May); Roots take-private at C$4.10 per share, about US$117M equity value and roughly US$134M implied EV, through operating partner JM&A Design and Development (definitive agreement, Aug 20) |
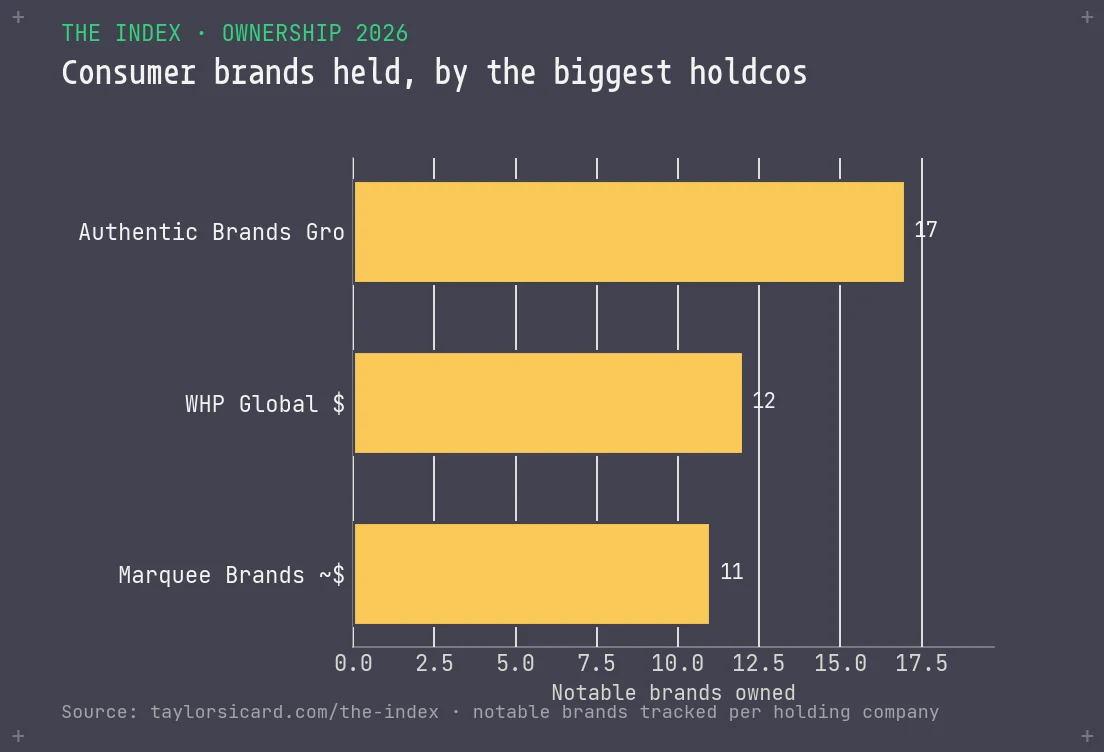
WHP Global generates over $8B in retail sales across a roster that includes Toys R Us, Vera Wang, Anne Klein, and Bonobos. Its headline 2026 move was buying Marc Jacobs from LVMH in a deal reported at $850M (with G-III Apparel as a partner), with the designer staying on as creative director. It also took a 50% controlling stake in Lands' End for $300M in cash, holding the IP and licensing while Lands' End runs its own DTC and B2B.
Marquee Brands runs about $5B in portfolio-wide retail sales across home, culinary, fashion, and active brands: Martha Stewart, Sur La Table, BCBG, Ben Sherman, Bruno Magli, Body Glove, and Dakine. In May 2026 it took a majority interest in Roberto Cavalli through a partnership with DAMAC Group, pushing further into luxury licensing.
The pattern to notice: when one of these three buys a brand, the brand usually keeps selling, but the economics change underneath. The holdco collects royalty streams and the operating risk moves to licensees. For a founder, being bought by a licensing holdco is a very different outcome than being bought by an operator, because the buyer is acquiring your name and your goodwill, not your team or your P&L. The operate-versus-license decision is the whole game at this end of the market.
Sources: Authentic Brands Group corporate brand portfolio; WHP Global brand list; Marquee Brands / DAMAC Group release (Businesswire, May 2026); Retail Dive and PR Newswire deal coverage; Consumer Deal Tracker (2026). Primary sources: the Guess SEC 8-K on the Authentic take-private and Authentic Brands Group's own release; the LVMH and WHP Global definitive agreement on Marc Jacobs.
The beauty houses, and
the brands sitting
inside each one.
Beauty is where DTC ownership concentrates fastest, because the category's high margins pull in acquirers and the strategics run active buy-side programs. Here's who owns what among the operating beauty houses, with each owner's most recognizable brands and its 2026 moves. These are operators, not licensors: they run the brands they own.
| Owner | DTC / consumer brands owned | 2026 moves |
|---|---|---|
L'Oreal | CeraVe, La Roche-Posay, Kiehl's, Lancome, YSL Beauty, NYX, Maybelline, Aesop, Youth to the People | Completed Kering Beaute incl. Creed (EUR 4B / ~$4.6B, Mar); bought Color Wow (Jan) and a majority of Medik8 (2026) |
Estee Lauder Cos. | The Ordinary / Deciem, MAC, Clinique, La Mer, Too Faced, Le Labo, Jo Malone, Tom Ford Beauty, Bobbi Brown, Aveda, Dr.Jart+ | Moved to full ownership of Forest Essentials (Mar); ended its sale process for Dr.Jart+, Too Faced and Smashbox in mid-July, keeping all three |
Unilever | Dove, Liquid I.V., Nutrafol, Paula's Choice, K18, Dermalogica, Tatcha, Living Proof, Hourglass, OLLY, SmartyPants | Bought Gruns supplement brand (~$1.2B reported, Apr); separating food and ice cream (Magnum) to become a beauty and wellbeing company |
Procter & Gamble | Ouai, Tula Skincare, Farmacy, First Aid Beauty, Native, SK-II (North America), Thorne | Bought Thorne from L Catterton for $3.8B (Aug), its largest consumer deal of the year, and Wonderbelly (Jan) |
Coty | CoverGirl, Rimmel, Sally Hansen, Kylie Cosmetics, philosophy, plus licensed fragrances (Gucci, Burberry, Hugo Boss) | Running a strategic review of its ~$1.2B Consumer Beauty division; signaled a possible sale or spin-off |
Henkel | Olaplex, Joico, Kenra, Schwarzkopf, Dial, Got2b, Persil | Bought Olaplex (~$1.4B take-private, Mar) from Advent International |
e.l.f. Beauty | e.l.f. Cosmetics, e.l.f. SKIN, Rhode, Naturium, Well People | Transferred Keys Soulcare back to founder Alicia Keys (May) |
Helen of Troy | Olive & June, Drybar, Curlsmith (Beauty & Wellness); Hydro Flask, OXO, Osprey (Home & Outdoor) | Olive & June ($240M) closed Dec 2024 |
Church & Dwight | Arm & Hammer, OxiClean, Trojan, Batiste, TheraBreath, Hero Cosmetics, Touchland | Bought Miss Mouth's Messy Eater (~$325M, May) out of the Thrasio estate; exited Flawless, Spinbrush, VMS, and the Waterpik showerhead line in 2025 |
L'Oreal is the largest beauty owner and the most active acquirer. Beyond mainstays like CeraVe, Kiehl's, and Aesop, its 2026 additions filled specific gaps: it completed the Kering Beaute acquisition in March for around EUR 4B, bringing in the House of Creed plus long-term fragrance licenses for Bottega Veneta and Balenciaga, and it bolted on Color Wow in professional haircare and a majority of the fast-growing skincare brand Medik8.
Estee Lauder Companies owns The Ordinary (through the Deciem family), MAC, Clinique, La Mer, Le Labo, Tom Ford Beauty, and Too Faced, among many others. It moved to full ownership of India's Forest Essentials in March 2026. A months-long process to sell Dr.Jart+, Too Faced, and Smashbox reached final bids in May, then died in mid-July when ELC told staff it will keep all three. A sale that gets walked back is its own signal: the bids came in below what the brands are worth inside the portfolio.
Unilever owns some of the biggest DTC wellness names: Liquid I.V. (a billion-dollar brand under Unilever ownership), Nutrafol, Paula's Choice, and K18, plus OLLY and SmartyPants. It bought the supplement brand Gruns in April 2026 (reported around $1.2B), and it is separating its food and ice-cream businesses to reposition as a beauty, wellbeing, and personal-care company, which tells you where its acquisition appetite is pointed.
e.l.f. Beauty owns Rhode, the Hailey Bieber brand it bought in a deal valued at up to $1B that closed in August 2025, alongside Naturium and Well People. In a telling move, e.l.f. transferred Keys Soulcare back to founder Alicia Keys in May 2026 to concentrate on its five core brands. Ownership at the strategic level is not permanent, and a strategic will hand a brand back when the fit stops working.
Henkel now owns Olaplex, which is the cleanest example on this whole map of why you check the seller, not just the buyer. Henkel bought Olaplex for roughly $1.4B in a take-private announced in March 2026. The seller was private-equity firm Advent International, which had held the brand. Advent was the seller here, not the buyer, and it turns up again in the next section as an active acquirer of a different brand.
Sources: L'Oreal 2025 annual report and Q1 2026 sales release; Estee Lauder Companies brand list and FY2026 filings; Unilever Beauty & Wellbeing brand pages and Gruns release; P&G Specialty Beauty; Henkel Olaplex release (Mar 2026); e.l.f. Beauty FY2026 10-K and BeautyMatter; Helen of Troy investor materials; Church & Dwight FY2026 filings; Consumer Deal Tracker (2026). Primary sources: L'Oreal's completion release for Kering Beaute; Estee Lauder's Forest Essentials release; Unilever's Liquid I.V. release; Henkel's Olaplex release and the Olaplex SEC 8-K; e.l.f. Beauty's rhode release; Helen of Troy's Olive & June SEC 8-K; Church & Dwight's Touchland SEC 8-K.
"The cleanest lesson on this map: check the seller, not just the buyer. Advent sold Olaplex to Henkel, then turned around and bought Salt and Stone."
The private-equity
platforms rolling up the
next tier.
Below the conglomerates, a set of private-equity platforms and new holding companies is assembling the next tier of ownership: sub-scale brands rolled into portfolios, or single brands bought as the seed of a platform. This is where a lot of 2026 mid-market DTC ownership landed, and it's the part of the map that changes fastest.
| Owner / platform | Brands owned | 2026 move |
|---|---|---|
HSG (HongShan) Private equity, with Temasek and True Light | Golden Goose (majority) | Completed a majority investment from Permira in June 2026, reported at about €2.5B enterprise value. Permira and Carlyle retain minority stakes. |
Advent International Private equity | Salt & Stone (majority) | Took a majority stake in Salt & Stone (Mar); separately, was the seller of Olaplex to Henkel |
Evermark (Yellow Wood Partners) ~$1.9B retail sales | Suave, ChapStick, Q-tips, St. Ives, Pond's, Noxzema, TIGI, VO5, Brut; Scholl's Wellness (Yellow Wood); Nestle Holistic Health VMS platform (Nature's Bounty, Osteo Bi-Flex, Ester-C, Nuun, Puritan's Pride, Sisu, Gard) pending | Formed by merging Suave Brands and Elida Beauty (Jan); Yellow Wood agreed to buy Nestle's mainstream VMS platform for US$1.0B, about 0.83x 2025 sales of US$1.2B, its sixth major carve-out (Sep 1), closing expected by H1 2027 |
Kindred Brands New holdco | Kinship | Kinship was its first acquisition (Mar); stated an "Honest Co.-like" platform ambition |
KYT Group Operator-led (ex-Honest, ex-CAA) | Glo Skin Beauty | Acquired Glo Skin Beauty (Mar) |
Skyline Beauty Group Amazon-heavy roll-up | LilyAna Naturals, plus five other brands; Lumin and Meridian (men's grooming) | LilyAna Naturals was its sixth brand (Mar); bought men's grooming brands Lumin and Meridian from Pangaea Holdings, about US$35M of sales over the last 12 months per CEO Joe Chen (undisclosed, Sep 1) |
Fundamental Brands Beauty holdco | Great American Beauty, Palm Beach Beaute | Definitive agreement for the brand and its licensing subsidiary (May) |
TSG Consumer Partners Private equity | Phlur, Saltair (majority) | Took a majority stake in Saltair (Jul), its second brand out of Prelude's The Center incubator after Phlur in 2025 |
Regent Private equity | Avon International; Avon North America (The Avon Company) pending | Agreed to buy Avon North America from LG H&H (undisclosed, Aug 24), reuniting it with Avon International, which Regent bought from Natura and Co. in January; expected to close September 1, 2026, with Lisa Siders as chief executive of the combined Avon |
Dollar Shave Club Stated multi-brand personal-care platform | Dollar Shave Club, Truly Beauty | Bought Truly Beauty, its first acquisition (undisclosed, Sep 1); both brands keep distinct identities, with supply chain and inventory integration starting immediately |
Advent International took a majority stake in Salt & Stone, the premium body-care and deodorant brand, in March 2026. Growth investor Humble Growth exited and founder Nima Jalali kept a minority position. The price was undisclosed, though reported comparable deals implied a valuation north of $500M, which is a rumored figure, not a confirmed one. The same firm that sold Olaplex to Henkel was buying body care in the same window, which is exactly how PE portfolios churn.
Evermark is the personal-care platform Yellow Wood Partners created in January 2026 by merging its Suave Brands and Elida Beauty portfolio companies into a single entity with roughly $1.9B in retail sales. It holds Suave, ChapStick, Q-tips, St. Ives, Pond's, Noxzema, TIGI, and international brands like VO5 and Brut. Yellow Wood separately owns Dr. Scholl's, which is why VKTRY Gear's performance insoles rolled up under Dr. Scholl's in 2026.
The rest are smaller platform seeds worth naming because they're where founder-scale brands are landing. Kindred Brands bought Kinship as its first deal, stating an ambition to build an Honest Company-style platform. KYT Group, run by former Honest and CAA executives, bought Glo Skin Beauty. Skyline Beauty Group added LilyAna Naturals as its sixth Amazon-heavy skincare brand. These are the early moves of holdcos that intend to own a lot more, which means the founders selling to them are betting on the platform, not just the check. That bet is the same one this blog examines in the mistakes holding companies make after they buy.
Sources: Advent International release (Mar 2026); Yellow Wood Partners / Evermark release (PR Newswire, Jan 2026) and Beauty Independent; Beauty Independent coverage of Kindred, KYT, Skyline, and Fundamental Brands; Yellow Wood Partners release on the Nestle VMS platform (PR Newswire, Sep 2026) and Nestle's divestment release (GlobeNewswire, Sep 2026); Regent release on Avon North America (PR Newswire, Aug 2026); Dollar Shave Club release on Truly Beauty (PR Newswire, Sep 2026) and Retail Dive; Beauty Independent on Skyline's Lumin and Meridian purchase (Sep 2026); Consumer Deal Tracker (2026).
The Amazon aggregators,
and what's left of
the model.
A few years ago the Amazon aggregators looked like they'd own a huge slice of DTC. They raised billions, bought hundreds of marketplace-native brands, and then hit a wall when interest rates rose and the roll-up math stopped working. The survivors are smaller and more selective, and this corner of the map is as much a cautionary tale as a directory.
| Aggregator | Status (2026) | Notable brands |
|---|---|---|
Thrasio | Emerged from Chapter 11 (2024); refocused on top performers | Beckham Hotel Collection, Angry Orange, Circadian Optics, Vybe Percussion, Sdara Skincare |
Razor Group | Merged with Perch (2024) | ~100+ brands across home, health, sports |
Olsam Group | Still acquiring selectively in 2026 | Wrinkles Schminkles (acquired 2026), plus its existing roster |
Thrasio raised more than $3B and peaked at a reported $10B valuation before filing for Chapter 11 in early 2024. It emerged four months later, shed around $495M in debt, and refocused on a handful of brands that actually make money, including Beckham Hotel Collection, Angry Orange, and Circadian Optics. Razor Group absorbed Perch in a 2024 restructuring, giving it a diversified roster of roughly 100-plus brands. Olsam Group is among the aggregators still buying selectively; it picked up Wrinkles Schminkles in 2026.
The sharpest single data point here is what happened to Miss Mouth's Messy Eater, the number-one stain remover on Amazon. It was sold out of the bankrupt Thrasio estate to Church & Dwight for around $325M in May 2026, at roughly 4.1 times sales and 11.6 times EBITDA. A genuinely good brand caught inside a broken aggregator got sold to a strategic in a bankruptcy process. The brand was fine. The owner wasn't. That gap between a healthy brand and an unhealthy owner is the whole reason knowing who owns a brand matters.
Sources: CNBC and Retail TouchPoints on the Thrasio Chapter 11 and exit; Razor Group / Perch release; Thrasio brand list; Church & Dwight Miss Mouth's release (May 2026); Consumer Deal Tracker (2026). Primary source: Church & Dwight's Miss Mouth's Messy Eater acquisition release.
The food and beverage
owners buying DTC-native
brands.
Food and beverage ownership is more fragmented than beauty, but the same dynamic holds: the DTC-native brands you know are increasingly owned by strategics, PE, and legacy CPG. Here are the 2026 moves that reset ownership on recognizable consumer food and drink brands. This is a slice of a much larger category, focused on the deals that put a well-known DTC or challenger brand under a new owner.
| Brand | New owner | Deal (2026) |
|---|---|---|
Huel Meal-replacement | Danone | ~$1.15B, ~3.4x sales (Mar) |
Made Group High-protein, APAC | Danone | ~$1.4B (Jul) |
yfood Meal-replacement, Europe | Nestle | Bought out founders for full ownership (Jun) |
S.Pellegrino, Perrier, Acqua Panna, Nestle Pure Life Water & premium beverages | Peranel (Nestle 50% / Platinum Equity 50%) | $5.6B EV carve-out JV (Jul) |
Good Culture Cottage cheese | L Catterton (majority) | ~$500M, rumored (Jan) |
Good Karma + No Cow Plant-based; protein bars | Trek One Capital | Same-day plant-based CPG deals (May) |
Bachan's Japanese BBQ sauce | The Marzetti Company | $400M, ~4.6x projected sales (Feb) |
YumEarth Organic candy | ACON Investments (control) | Undisclosed (Jul) |
La Terra Fina Dairy-based dips, spreads, quiche | Sargento Foods | Undisclosed (Jul) · closes late Sept |
Dalston's Soda Co Better-for-you soda, UK | Damm UK (5%) | Six-figure sum for 5% (reported, Jul) · production moves to Damm's Bedford brewery |
My/Mochi Ice Cream Mochi ice cream, US | Morinaga & Co. (Japan) | Undisclosed (Mar announced, Apr closed) · joins HI-CHEW and Chargel under Morinaga America, stays in Los Angeles |
Jamieson Wellness Vitamins, minerals and supplements, Canada | Kirin Holdings | C$45.75 per share, about C$2.0B fully diluted equity and C$2.5B EV (Aug) · definitive agreement, not yet closed: shareholder vote expected September, closing targeted for Q4 2026 |
Woof Pupsicle, refillable dog enrichment | The Farmer's Dog | Undisclosed (Aug) · definitive agreement, becomes an independent division of The Farmer's Dog, closing in 2026 |
VITHIT Functional soft drinks, Dublin | Nichols plc (Vimto) | EUR 75M (GBP 64M) cash, about 2.8x 2025 revenue (Aug) · all cash, debt-free cash-free, funded from the balance sheet; VITHIT posted EUR 26.5M of 2025 revenue at a 15.8% operating margin |
Pets Deli Premium DTC dog and cat nutrition, Berlin | VAFO Group | Undisclosed (Aug) · more than EUR 40M of annual turnover, founded 2013 by Tania Moser; VAFO frames it as a D2C and digital growth platform for its European portfolio |
BÉIS Lifestyle and travel bags, El Segundo | Samsonite Group | $210M total enterprise value, about 1.0x 2025 revenue, $178.5M for 85% of equity (Aug) · definitive agreement, not yet closed: expected Q4 2026 subject to regulatory approval. Founder Shay Mitchell rolls over roughly half her equity to retain 15% |
Saputo UK dairy (Cathedral City, Wensleydale, Davidstow, Clover, Country Life) Branded and private-label dairy, United Kingdom | B.S.A. SAS (Lactalis) | GBP 988M enterprise value (about C$1.86B), roughly 0.8x trailing revenue (Aug) · agreement to sell Saputo's entire UK operation including five manufacturing facilities; closes by the end of Q1 calendar 2027 subject to regulatory approval |
Hot Topic, Inc. (Hot Topic, BoxLunch, Her Universe) Specialty retail, apparel and merchandise | Spencer Spirit Holdings, from Sycamore Partners | About $350M, Bloomberg-reported, terms not disclosed in the release (Aug 6) · definitive agreement ending Sycamore's 13-year hold; combines six merchandise concepts past 3,000 North American stores, CEO Steve Vranes stays and the brands keep their California headquarters |
Chobani Greek yogurt and dairy, US | Chobani (Keurig Dr Pepper exits its equity stake) | US$800M for KDP's full stake, bought back by Chobani, plus about US$125M for KDP's Allentown, PA plant and warehouse, about US$925M combined (Sep 1) · both transactions expected to close in Q3; Chobani keeps co-manufacturing certain products for KDP at Allentown for a defined period |
UNTUCKit Menswear, about 70 US stores plus ecommerce | Randa Apparel & Accessories | Undisclosed (Sep 1) · brand and operations; founders Chris Riccobono and Aaron Sanandres stay and run day-to-day, and UNTUCKit remains a stand-alone business rather than being integrated into Randa. WWD estimates about US$200M to US$250M of sales, reported not confirmed |
GOODLES (Gooder Foods) Better-for-you boxed mac and cheese, US | Barilla Group | Undisclosed (Sep 2) · agreement to acquire; US$70M of US retail sales in 2024 and about 6% of the US mac and cheese market by 2025, last priced at US$88M on the September 2023 Series A led by L Catterton. Founders Jen Zeszut and Paul Earle stay and the brand runs standalone. Barilla has disclosed no price on any of its last four deals |
North American Breweries, formerly FIFCO USA (Labatt USA, Genesee, Seagram's Escapes, Dundee, Lipton Hard Iced Tea, Bubly Wine Refresher) US regional beer and flavored malt, plus contract brewing | Saothair Capital Partners, from Heineken | Undisclosed (Sep 3) · completed; the business reverts to its former name. Peter Bodenham becomes CEO, and Saothair operating partner Rich Lozyniak ran North American Breweries from 2009 to 2014. Bank of America advised Heineken |
Twinlab, Reserveage, Metabolife, Alvita Tea, RipFuel Legacy supplements, sports nutrition and longevity wellness | cbdMD, Inc. (NYSE American: YCBD) | Undisclosed (Sep 2) · definitive agreement, a distressed asset purchase through an assignment for the benefit of creditors and subject to court approval, so the brands change hands out of an insolvency process rather than from a going-concern seller. Combined trailing twelve month revenue to June 2026 of roughly US$30M |
bback, formerly BounceBack Alcohol recovery, hydration and liver wellness supplements, Singapore | DSG Consumer Partners, from Evo Commerce | Undisclosed (Sep 2) · completed; more than 400 points of sale in Singapore including Guardian and Watsons plus ecommerce, and more than 100,000 customers claimed across 10 markets, having raised about US$4.7M in total. Saket Gore, former Asia Pacific CEO of Himalaya Wellness, installed as CEO |
The names to know at the strategic top: Danone bought Huel for roughly $1.15B in March 2026 and agreed to buy Australia's Made Group for about $1.4B in July, pushing hard into high-protein and meal replacement. Nestle took full ownership of Europe's yfood in June after holding a minority stake since 2023, while separately shedding its roughly $1.3B ice-cream business. On the financial-buyer side, L Catterton took a majority of Good Culture (rumored around $500M), and Trek One Capital picked up Good Karma and No Cow in a single day of plant-based dealmaking.
The takeaway mirrors beauty: a food or beverage brand that feels independent on the shelf is often owned by Danone, Nestle, a private-equity sponsor, or a legacy CPG holdco. If you're tracking a challenger brand, the ownership line tells you whether it has a giant's distribution behind it or a sponsor's return clock ticking on it. For the wider view of who's buying across every consumer category this year, the 2026 consumer M&A window is the pillar.
Sources: DairyReporter and Australian Financial Review on the Danone deals; Nestle and Drew Fallon reporting on yfood; BevNET / NOSH on Trek One Capital; Keurig Dr Pepper investor-relations release and Food Dive on the Chobani stake sale (Sep 2026); Randa release (PR Newswire) and WWD on UNTUCKit (Sep 2026); Spencer Spirit Holdings release (PR Newswire) and Bloomberg Law on Hot Topic (Aug 2026); company releases; Consumer Deal Tracker (2026). Rumored and reported figures labeled as such. Primary sources: Danone's release on acquiring Huel; Nestle's release on taking full ownership of yfood.
Four kinds of owner,
and why the type
tells you the most.
The framing behind the map. Nearly every consumer brand that changes hands lands with one of four owner types, and the type tells you more about how the brand will be run than the specific name does. Sort a brand into the right bucket and you already know most of what matters about its future.
The first type is the strategic house of brands: an operating company like L'Oreal, Unilever, e.l.f. Beauty, or Procter & Gamble that buys brands to run them, fold them into shared manufacturing and distribution, and grow them inside a portfolio. These owners actually operate the brands. They set the biggest headline prices because they can underwrite the distribution and manufacturing overlap a financial model cannot put a number on.
The second type is the asset-light brand-licensing holdco: Authentic Brands Group, WHP Global, Marquee Brands. These firms buy the intellectual property, the trademark and the name, then license the operations to third parties who make and sell the product. They own the brand without running the day-to-day. It is a fundamentally different model, and it is why one holdco can own fifty brands with a fraction of the operating headcount an operator would need.
The third type is the private-equity roll-up platform: a sponsor like Advent International or Yellow Wood Partners that acquires several sub-scale brands, centralizes the unglamorous functions, and underwrites a return on cash flow rather than on the distribution a strategic already owns. This is the model behind the private-equity roll-up of consumer and celebrity brands, and it sits underneath a growing share of mid-market ownership.
The fourth type is the Amazon aggregator: firms like Thrasio and Razor Group that bought up marketplace-native brands at scale, hit a wall when rates rose, and are now a smaller, more selective corner of the market. Some of the most cautionary ownership stories of the last two years live here.
Two clarifications that keep this map honest. First, "owns" is not the same as "operates." A licensing holdco owns the name; the operator running it under license is a different company. I flag which is which. Second, this is a living map. Ownership changes with every deal, and 2026 has been a busy year, so treat every row as current to July 2026 and sourced to the transaction that set it. When a brand moves, the map moves.
Rhode is owned by e.l.f. Beauty. Olaplex is owned by Henkel. Liquid I.V., Nutrafol, and Paula's Choice are owned by Unilever. Marc Jacobs and Lands' End (controlling stake) are owned by WHP Global. Guess, Reebok, and Lee are owned by Authentic Brands Group. Salt and Stone is owned by Advent International. The Ordinary is owned by Estee Lauder Companies. Aesop, CeraVe, and Color Wow are owned by L'Oreal. Touchland and Hero Cosmetics are owned by Church & Dwight. Huel is owned by Danone. Suave, ChapStick, and Q-tips are owned by Evermark (Yellow Wood Partners). The full sourcing for each sits in the tables above.
What the owner actually
changes about a
brand.
Reference data is only useful if you know why it matters. So here's the operator's read on what changes the moment a brand's owner does, drawn from the years I spent deciding which brands to bring into a portfolio and watching what happened after the close.
The pricing discipline changes. A strategic owner will often protect a brand's positioning and invest behind it. A private-equity owner runs it to a return and a timeline, which usually means margin discipline, shared services, and a planned exit inside three to five years. A licensing holdco cares mostly about the royalty stream and brand equity, not the operating detail. The same brand behaves differently under each, and if you're a supplier, a partner, or a competitor, the owner tells you which playbook to expect.
The shared-services stack changes. When a brand joins a house of brands, the unglamorous functions get centralized: sourcing, fulfillment, finance, media buying. That can lift margin fast, but it can also strip out the specific things that made the brand distinctive if the integration is clumsy. I've seen both. The good integrations keep the brand's voice and centralize only the plumbing. The bad ones flatten the brand into the portfolio and wonder why the growth stalled.
The exit clock changes. A founder-owned brand can compound patiently. A sponsor-owned brand is on a clock from day one, which shapes every decision toward the eventual sale. Knowing whether a competitor is early or late in its owner's hold period tells you a lot about how aggressively it will behave. A brand two years into a five-year PE hold is playing a different game than one that just got bought.
For founders, the owner sets the ceiling. This is the part I'd underline. Where your brand belongs is a strategic question you should answer years before you sell, because the buyer type sets the multiple, the structure, and what happens to your team after the close. A brand built for a strategic needs a growth curve and a category position worth owning. A brand built for a PE platform needs clean, defensible cash flow. A brand headed for a licensing holdco is really selling its name. Trying to be attractive to all three usually means being compelling to none, which is the same lesson that runs through what a realistic DTC exit actually looks like and the diligence red flags that make a buyer walk.
If you want the price side of this, the multiples different beauty acquirers pay shows how the owner type maps to the number. Ownership and valuation are two views of the same question: who should own this brand, and what will they pay to.
The through-line of this whole map is simple. The name on the box is not the owner. Rhode is e.l.f. Olaplex is Henkel. Liquid I.V. is Unilever. Marc Jacobs is WHP Global. Salt and Stone is Advent. Most of the DTC brands that feel independent sit inside a strategic, a licensing holdco, a private-equity platform, or an aggregator, and the owner type shapes how the brand gets run, priced, and eventually sold. This page is the reference for who owns what now. Because ownership moves with every deal, I'll keep it current, and the sources are here so you can verify any row yourself. I refresh this map weekly at a minimum, and more often when new ownership intel lands, sometimes several times a day. It was last updated September 21, 2026.
Every brand, by
category.
1190 brands in 7 categories. Each category has its own page listing every brand, its owner, the price where one was disclosed, and the source.
| Category | Brands mapped | Owners | Largest owner | Full list |
|---|---|---|---|---|
Food & bev | 461 | 323 | Sazerac (Buffalo Trace owner) (7) | All 461 food & bev brands |
Beauty | 238 | 163 | L'Oreal (9) | All 238 beauty brands |
Apparel | 200 | 153 | Authentic Brands Group (IP), with Vince Holding Corp taking the operating business (7) | All 200 apparel brands |
Wellness | 103 | 86 | Nestle (Health Science) (4) | All 103 wellness brands |
Pet | 89 | 72 | Manna Pro Products (4) | All 89 pet brands |
Home | 64 | 55 | 3Z Brands (2) | All 64 home brands |
Other | 35 | 28 | MacNeill Pride Group (2) | All 35 other brands |
Knowing who owns your competition tells you who your likely buyer is, and how patient their capital is. That mapping is the first thing I do on a positioning or exit engagement.
The owners holding
more than one brand.
131 owners hold two or more of the mapped brands, 372 brands between them. The rest of the map is single-brand owners, listed on the category pages.
| Owner | Brands held | Brands |
|---|---|---|
L'Oreal | 9 | Aesop, ColorWow, Creed Fragrance and Kering beauty/fragrance licences, Gucci beauty and fragrance licence, Medik8, Mugler brands and Azzaro fragrances, Skinbetter Science, Thayers Natural Remedies, Youth to the People |
Unilever | 9 | Aquis Hairsciences, Dr. Squatch, K18, Liquid I.V., Nutrafol (Nutraceutical Wellness), Onnit, Paula's Choice, Wild, Yasso |
Authentic Brands Group (IP), with Vince Holding Corp taking the operating business | 7 | Champion (HanesBrands), Dockers, Hunter Boots (intellectual property), PVH Heritage Brands (Izod, Van Heusen, Arrow, Geoffrey Beene), Reebok, Ted Baker, Vince (intellectual property) |
L Catterton | 7 | Beauty Industry Group, Birkenstock, Ex Nihilo, Just Over The Top (JOTT), KIKO Milano, Stripes Beauty, Thorne HealthTech (Unilever approach) |
Sazerac (Buffalo Trace owner) | 7 | 818 Tequila, BuzzBallz, Dirty Shirley, Lough Gill Distillery, SIPMARGS, SVEDKA, Western Son Vodka |
Bansk Group | 6 | Arcadia Consumer Healthcare, BYOMA, Foundation Wellness, No Man's Land Foods, PetIQ (Bansk Group portfolio), amika and Eva NYC |
Diageo | 6 | 21Seeds, Don Papa, Lobos 1707, Lone River Ranch Water, Loyal 9 Cocktails, Mezcal Union |
Mars, Incorporated | 6 | Hotel Chocolat, Hotel Chocolat Group plc, KIND North America, Kellanova, Kevin's Natural Foods, Tru Fru |
Mondelez International | 6 | Chipita, Clif Bar & Company, Evirth, Give & Go Prepared Foods, Grenade, Hu |
Advent International | 5 | Parfums de Marly and Initio Parfums Prives (Sprecher Berrier Group), Sauer Brands, Seek Pet, Zimmermann, bareMinerals, BUXOM and Laura Mercier |
Constellation Brands | 5 | Austin Cocktails, Empathy Wines, HOP WTR (remaining interest), Lingua Franca, Sea Smoke Estate Vineyards |
Ferrero | 5 | Burton's Biscuit Company, Power Crunch, Purely Elizabeth, WK Kellogg, Wells Enterprises |
KKR | 5 | Natural Pet Food Group, The Wella Company, Varsity Brands (BSN Sports, Varsity Spirit, Herff Jones), Vini Cosmetics, Wella, Clairol, OPI and ghd (Coty Professional and Retail Hair) |
PepsiCo (PEP) | 5 | Poppi, Rockstar Energy, Sabra Dipping Company and Obela (remaining 50%), Siete Foods, poppi (VNGR Beverage) earn-out |
Starco Brands, Inc. (OTCQB: STCB) | 5 | AOS Group (Art of Sport), Custom Bakehouse, Skylar, Skylar Body, Soylent |
American Exchange Group | 4 | HatchCollective, Indie Lee, Island Surf Company, Urban Skin Rx |
Chobani, buying back from Keurig Dr Pepper | 4 | Chobani (KDP equity stake) plus KDP's Allentown, PA plant, Chobani equity stake held by Keurig Dr Pepper, plus KDP's Allentown, PA manufacturing facility and warehouse, Daily Harvest, La Colombe (33% stake) |
Church & Dwight | 4 | Graphico Inc., Hero Cosmetics, Miss Mouth's Messy Eater, Touchland |
E. & J. Gallo Winery | 4 | Bev, LIQS Premium Cocktail Shots, RumChata, Whiny Baby |
FullBeauty Brands | 4 | Avenue (Avenue Stores and eight sub-brands), Cuup, Dia & Co., Eloquii |
Keurig Dr Pepper | 4 | Dyla Brands, GHOST, JDE Peet's, Limitless |
Manna Pro Products | 4 | Bullymake, Dinovite, Doggie Dailies, ZuPreem |
Nestle (Health Science) | 4 | Nuun, Orgain, The Bountiful Company (Nature's Bounty, Solgar, Osteo Bi-Flex, Pure Protein), Vital Proteins |
Platinum Equity (50%) | 4 | F.lli Polli S.p.A., Horizon Organic and Wallaby, Mad Engine, Pelican Products |
Post Holdings | 4 | 8th Avenue Food & Provisions, Rachael Ray Nutrish, Nature's Recipe, 9Lives, Kibbles 'n Bits and Gravy Train (Smucker pet food), Ronzoni, TreeHouse Foods ready-to-eat cereal business |
Procter & Gamble | 4 | Farmacy Beauty, Ginger Health, Mielle Organics, OUAI |
Puig | 4 | Byredo, Dr. Barbara Sturm, Kama Ayurveda, Loto del Sur |
The Hershey Company | 4 | Dot's Homestyle Pretzels, LesserEvil, Lily's Sweets, Sour Strips |
WHP Global (+ G-III) | 4 | G-Star Raw, Joseph Abboud, Lotto global trademarks, Vera Wang (brand intellectual property) |
Yellow Wood Partners | 4 | Elida Beauty (Q-Tips, Caress, TIGI, Timotei, St. Ives and Pond's in NA/Europe, Brut, VO5, Alberto Balsam), Nestle Holistic Health VMS platform (Nature's Bounty, Osteo Bi-Flex, Ester-C, Gard, Nuun, Puritan's Pride, Sisu, plus the US private-label supplements business), PlusOne, Suave (North America) |
Antelope | 3 | Ark Naturals, Bocce's Bakery, My Perfect Pet |
B&G Foods | 3 | Crisco, Del Monte broth brands (College Inn, Kitchen Basics), Farmwise Foods (Veggie Fries) |
Bluestar Alliance | 3 | Dickies, Off-White, Scotch & Soda |
Essity | 3 | Edgewell North America feminine care portfolio, Edgewell feminine care business, Knix Wear |
Estee Lauder | 3 | DECIEM (The Ordinary, NIOD, Hylamide), Forest Essentials, Tom Ford |
Full Glass Wine | 3 | Cameron Hughes Wine, Splash Wines, Wine Access |
Gordon Brothers | 3 | Cels Brands (Chinese Laundry, Dirty Laundry, CL by Laundry, 42 Gold), LK Bennett (brand and IP), Radley London |
Grove Collaborative | 3 | 8Greens, Grab Green, Sundaily |
Helen of Troy | 3 | Curlsmith (Recipe Products Ltd.), Olive & June, Osprey Packs |
Henkel | 3 | Not Your Mother's, Shiseido Asia-Pacific Hair Professional business, Vidal Sassoon brand and hair care business in Greater China |
Molson Coors | 3 | Atwater Brewery, Blue Run Spirits, Cruz Blanca Brewery |
Next In Natural | 3 | Aura Bora, Lavva, Rowdy Mermaid |
Our Home | 3 | Good Health and R.W. Garcia, ParmCrisps, Pop Secret |
Second Nature Brands | 3 | Sahale Snacks, Tillamook Country Smoker, Voortman |
Sycamore Partners | 3 | Ann Taylor, Loft, Lane Bryant and Lou & Grey, Chico's FAS (Chico's, White House Black Market, Soma), Ste. Michelle Wine Estates |
Tilray Brands | 3 | Carlsberg beverage brand licence (Tilray), Hiball plus eight craft beer brands (Shock Top, Breckenridge, Blue Point, 10 Barrel, Redhook, Widmer Brothers and others), Hop Valley Brewing, Terrapin Beer Co., Revolver Brewing and Atwater Brewery |
e.l.f. Beauty | 3 | Naturium, W3LL PEOPLE, rhode |
3Z Brands | 2 | Nolah Sleep, Southerland |
A.K.A. Brands | 2 | Culture Kings, Mnml |
AUA Private Equity Partners | 2 | Tropical Cheese, Western Smokehouse |
AURELIUS | 2 | Hain Celestial international business (Ella's Kitchen, Linda McCartney Foods, Hartley's, Joya, Natumi, Cully & Sully, Yorkshire Provender, New Covent Garden), The Body Shop |
Amorepacific | 2 | COSRX, Tata's Natural Alchemy |
Amyris | 2 | Costa Brazil, MenoLabs |
Assisi Pet Care (Wind Point Partners) | 2 | Forthglade, Sniffers Pet Care, brand NAW |
B.S.A. SAS (Lactalis) | 2 | Saputo Dairy Division (UK), Saputo UK dairy operation |
Bacardi | 2 | D'USSE Cognac, Ilegal Mezcal |
Bain Capital | 2 | Valeo Foods, Vitabiotics Group |
Blackstone | 2 | Real Pet Food Company, Spanx |
Boosted Ecommerce | 2 | Appelson, Happy Healthy Hippie |
Coca-Cola | 2 | BodyArmor, Fairlife LLC |
Creations Foods | 2 | Moon Cheese, REAL Cookies |
Crown Brands Group | 2 | Cosabella, Hanky Panky |
DDC Enterprise (DayDayCook) | 2 | Nona Lim, Yai's Thai |
Danone | 2 | Follow Your Heart (Earth Island), Kate Farms |
Designer Brands | 2 | Keds, Topo Athletic |
Edgewell Personal Care | 2 | Billie, CREMO |
FabFitFun | 2 | Paya Health, PupBox |
Fairfax Financial Holdings | 2 | Andrew Peller Limited (TSX: ADW.A, ADW.B), Peak Achievement Athletics (Bauer Hockey) |
Ferrara Candy | 2 | Dori Alimentos, Jelly Belly |
Flowers Foods | 2 | Papa Pita Bakery, Simple Mills |
Foley Family Wines | 2 | Chateau St. Jean, Silverado Vineyards |
Food52 | 2 | Dansk, Schoolhouse |
Fundamental Brands Inc. | 2 | Amala, Lucky Heart |
Galaxy Universal | 2 | And1, Avia, Gaiam and SPRI, Reebok Design Group and U.S. operations |
Gauge Capital | 2 | BondiBoost, Coco & Eve |
General Mills | 2 | Fera Pet Organics, Tyson Foods pet treats business (Nudges, Top Chews, True Chews) |
Grupo Bimbo | 2 | Emmy's Organics, Modern Foods |
Gryphon Investors | 2 | Metagenics (Gryphon Investors), Revision Skincare and Goodier Cosmetics |
Highlander Partners | 2 | Ergobaby, RMS Beauty |
International Beverage | 2 | Cardrona Distillery, Larsen Cognac |
Ironbridge Equity Partners | 2 | Handi Foods, King's Pastry |
J&J Snack Foods | 2 | Dippin' Dots, Thinsters |
John B. Sanfilippo & Son | 2 | Just the Cheese, TreeHouse Foods snack bar business |
Joy Group | 2 | Biophyto Genesis, Foltene |
Kimberly-Clark | 2 | Kenvue, Thinx |
Kraft Heinz | 2 | Hemmer, TGI Fridays frozen appetizers licence (revised, in perpetuity) |
LG Household & Health Care | 2 | Arctic Fox (Boinca), Hince (via Vivawave) |
Lactalis | 2 | Kraft Heinz natural cheese business (Cracker Barrel, Breakstone's and others), Marie Morin Canada |
Lolë Brands | 2 | Louis Garneau, Sugoi and Sombrio, Sanuk |
Luxury Brands | 2 | BIA Skin, Prai Beauty |
MacNeill Pride Group | 2 | GCI Outdoor, Klymit |
Marquee Brands | 2 | Roots Corporation (TSX: ROOT), totes Isotoner Corporation |
McCormick | 2 | Cholula Hot Sauce, Unilever Foods business (Knorr, Hellmann's) |
Nestle | 2 | Freshly, SimplyCook |
Next Century Spirits | 2 | Grain & Barrel Spirits brand portfolio, XED Beverage |
Nexus Capital Management | 2 | Cheeze Kurls, MAV Beauty Brands (Marc Anthony True Professional, Renpure, Cake Beauty, The Mane Choice) |
No Sleep Beverage | 2 | No Sleep Beverage, Whiskey Del Bac, Nine Banded Whiskey, Ume Plum Liqueur |
Paine Schwartz Partners | 2 | Promix Nutrition, Suja Life, Inc. |
Partner in Pet Food | 2 | Landini Giuntini, Mispol Group |
Pattern Brands | 2 | Onsen, Yield and Poketo |
Paw Acquisition | 2 | Handicappedpets, Muffin's Blind Dog Clubhouse |
Pernod Ricard | 2 | Chateau Sainte Marguerite, Skrewball Spirits |
PetIQ (Bansk Group portfolio) | 2 | MYOS Corp (Fortetropin), Rocco & Roxie Supply |
Prime Drink Group Corp (CSE: PRME) | 2 | Prime Capital Investments (Beach Day Every Day), Prime Capital Investments Inc, parent of the Beach Day Every Day (BDED) brand |
Restoration Hardware (NYSE:RH) | 2 | Dennis & Leen, Michael Taylor Designs |
Rhodium | 2 | SIO Beauty, Solomomo |
Richards Group (OTC: RPKIF), via Healthmark Services | 2 | PharmaSystems CPG division, PharmaSystems Inc., consumer packaged goods division (PSI CPG) |
Seneca Foods | 2 | Green Giant U.S. Frozen business, Green Giant US shelf-stable and canned business |
Silverwood Brands | 2 | Nailberry, Sonotas |
Sleep Country Canada | 2 | Casper (Canadian operations), Sleep Number |
Society Brands | 2 | Crunchi, Primal Life Organics |
SuanNutra (Carbyne Equity Partners portfolio company) | 2 | IFF botanical extracts, VMS and food enhancement portfolio, IFF botanical extracts, vitamins and minerals, and food enhancement portfolio |
The Campbell's Company | 2 | La Regina di San Marzano di Antonio Romano S.p.A. and La Regina Atlantica, LLC, Sovos Brands |
The Carlyle Group | 2 | Beautycounter (Counter Brands), Every Man Jack |
The Wine Group | 2 | St. Agrestis (Phony Negroni), Wine brands and production facilities of Constellation Brands |
Treasury Wine Estates | 2 | Daou Vineyards, Frank Family Vineyards |
TreeHouse Foods | 2 | Bick's, Habitant, Woodman's and McLarens, Regional pasta brand maker acquired by TreeHouse Foods |
USANA Health Sciences | 2 | Hiya Health Products, Rise Bar / Oola Global |
Unilever (Hindustan Unilever) | 2 | Minimalist, OZiva (Zywie Ventures) |
United Legwear & Apparel Co. | 2 | Pro Player, TicTacToe |
United Sports Brands | 2 | Glukos Energy, Pearl Izumi |
Utz Brands (UTZ) | 2 | H.K. Anderson, Truco Enterprises (On The Border tortilla chips, salsa, queso) |
VAFO Group (Czech Republic) | 2 | Pets Deli, Pooch & Mutt |
Vida Shoes International | 2 | Aquatalia, Donald Pliner |
Vista Outdoor | 2 | Fox Head (Fox Racing), Simms Fishing Products |
Voff Premium Pet Food | 2 | Carnibest, Energique |
WSG Brands | 2 | Nasty Gal, Von Dutch |
West Lane Capital Partners | 2 | Mented Cosmetics, Seven |
Wipro Consumer Care and Lighting | 2 | Dermatouch, S Brands Consumer Care |
n/a | 2 | Hyper Skin, The Simply Good Foods Company (Nasdaq: SMPL) / OWYN |
private equity buyer | 2 | Chef Boyardee, Pet Ventures / Pet 'n Shape |
Brands sold, then
sold again.
| Brand | Earlier owner | Earlier sale | Current owner | Latest sale |
|---|---|---|---|---|
Au Vodka | Sazerac (Buffalo Trace owner) | Aug 17, 2026 | Sep 14, 2026 | |
BELLA+CANVAS | SanMar | May 18, 2026 | Jun 25, 2026 | |
BeatBox Beverages | Anheuser-Busch | Dec 5, 2025 | Anheuser-Busch InBev | Feb 27, 2026 |
Billie | Procter & Gamble | Jan 8, 2020 | Edgewell Personal Care | Oct 1, 2021 |
Birch Benders | Sovos Brands | Aug 27, 2020 | Hometown Food Company (Brynwood Partners) | Jan 10, 2023 |
Boardriders (Billabong, Quiksilver, Roxy, RVCA, DC Shoes, Element) | Authentic Brands Group (IP), with Vince Holding Corp taking the operating business | Apr 4, 2023 | C.C.V. Beaumanoir | May 6, 2024 |
Casper Sleep | Durational Capital Management | Jan 25, 2022 | Carpenter Co. | Nov 4, 2024 |
Champion (HanesBrands) | G-III Apparel Group | Sep 7, 2023 | Authentic Brands Group (IP), with Vince Holding Corp taking the operating business | Jun 5, 2024 |
Cosabella | CALIDA Group | May 19, 2022 | Crown Brands Group | Jul 28, 2026 |
Ex Nihilo | Jan 23, 2026 | L Catterton | Feb 1, 2026 | |
Glamorise Foundations | Wacoal International | Mar 30, 2026 | Apr 1, 2026 | |
Go-To Skincare | BWX Limited | Jul 1, 2021 | Zoe Foster Blake and Paul Bates (founder buyback) | Dec 20, 2023 |
Golden Goose | Permira | Feb 12, 2020 | HSG with Temasek | Jun 25, 2026 |
Good Karma Foods | Good Karma Foods management | Aug 25, 2020 | May 18, 2026 | |
Great American Beauty + Palm Beach Beaute | Fundamental Brands Inc. | Apr 28, 2026 | May 7, 2026 | |
Grown Alchemist | L'Occitane Group | Jan 1, 2022 | Andre Hoffmann (former L'OCCITANE Vice-Chairman and CEO) | Apr 2, 2024 |
Guess (IP majority) | Authentic Brands Group (IP), with Vince Holding Corp taking the operating business | Jan 23, 2026 | Jan 23, 2026 | |
Handicappedpets | Lintbells | Dec 12, 2022 | Paw Acquisition | Aug 2, 2024 |
Lee (denim IP) | May 21, 2026 | Shanghai Huizhong Technology (HiMaxx) | Sep 2, 2026 | |
Love Your Melon | Win Brands Group | Feb 1, 2022 | founder (reacquisition) | Sep 18, 2025 |
MADE Group (Coco Bella, The Collective, Hooray, Rokeby) | Danone | Jun 22, 2026 | Jul 2, 2026 | |
Made by Nacho | I and Love and You | Jan 1, 2026 | Mar 17, 2026 | |
No Cow | May 18, 2026 | Trek One Capital | Jun 1, 2026 | |
Noted. Aromas | eComplete; NVM Private Equity | Oct 1, 2025 | Jan 9, 2026 | |
Olaplex | Advent International | Jan 15, 2020 | Mar 26, 2026 | |
Power Crunch | Ferrero (USA) | Jan 24, 2025 | Ferrero | Sep 2, 2026 |
Protein Works | Lactalis | Apr 1, 2026 | Jun 4, 2026 | |
Punch'd Energy | The Neighborhood Beverage Company | Mar 31, 2026 | Apr 2, 2026 | |
Pura Vida | Vera Bradley | Jan 30, 2023 | Edible Brands | Mar 21, 2025 |
Richer Poorer | Francesca's | May 2, 2023 | Andie | May 20, 2025 |
STEM Animal Health | Kane Biotech | Dec 20, 2023 | Dechra Pharmaceuticals | Apr 11, 2024 |
Sleep Number | Jun 18, 2026 | Sleep Country Canada | Jul 21, 2026 | |
Sniffers Pet Care, brand NAW | May 8, 2026 | Assisi Pet Care (Wind Point Partners) | Jul 1, 2026 | |
Stone Brewing | Sapporo U.S.A. | Jun 24, 2022 | Firestone Walker Brewing and Duvel Moortgat USA (from Sapporo USA) | Apr 21, 2026 |
Supreme | VF Corp. | Nov 9, 2020 | EssilorLuxottica | Jul 17, 2024 |
The Creme Shop | LG Household & Health Care | Apr 20, 2022 | LG H&H Co., Ltd. (KRX: 051900) | May 30, 2025 |
Weider Nutrition International | Sunway Group | Apr 1, 2026 | Sunway Biotech (Bora Group) | May 5, 2026 |
Whole Earth Brands | Sweet Oak Parent, an affiliate of Sababa Holdings FREE, LLC (Sir Martin E. Franklin), with Rhone Capital VI as indirect owner | Feb 13, 2024 | Heartland Food Products Group | May 27, 2026 |
YumEarth | ACON Investments | Jun 30, 2026 | Jul 2, 2026 |
Sales announced,
then called off.
3 announced sales have a public report that they fell through, newest first. The map above leaves these buyers out.
| Brand | Announced buyer | Announced | What happened | Category | Source | Also cited |
|---|---|---|---|---|---|---|
Brown-Forman / Pernod Ricard combination | Mar 26, 2026 | In talks for a spirits mega-merger | Food & bev | x.com | ||
Capri Holdings (Michael Kors, Jimmy Choo, Versace) | Tapestry | Aug 10, 2023 | Both boards approved; close expected in 2024 subject to shareholder and regulatory approval. The deal was later blocked and abandoned. | Apparel | retaildive.com | |
iRobot | Amazon | Aug 5, 2022 | Definitive agreement for the Roomba maker; the deal later drew FTC scrutiny and was ultimately abandoned in 2024. | Home | retaildive.com |
Where does your brand belong, and what would an owner pay for it?
I've sat on the buy side deciding which brands to fold into a nine-figure house of brands, and built brands worth acquiring. If you're a year or two from a potential exit, I can tell you which owner type fits your brand, what they'll actually pay, and what's quietly capping the number, before a buyer runs the process on you. The form takes two minutes.
Start a conversation DTC growth consultant →Who owns what: the
questions people
actually search.
Who owns Rhode?
Rhode is owned by e.l.f. Beauty, which acquired Hailey Bieber's brand in a deal valued at up to $1B, structured as roughly $800M at closing plus a $200M earnout tied to performance. The acquisition closed in August 2025, and Rhode now sits alongside e.l.f. Cosmetics, e.l.f. SKIN, Naturium, and Well People. e.l.f. transferred Keys Soulcare back to founder Alicia Keys in May 2026 to focus on those five brands.
Who owns Olaplex?
Olaplex is owned by Henkel, the German consumer-goods group behind Schwarzkopf, Dial, and Persil. Henkel agreed to buy Olaplex for roughly $1.4B in a take-private deal announced in March 2026, adding it to a premium hair-care portfolio that includes Joico and Kenra. The seller was private-equity firm Advent International, which had held Olaplex. Advent was the seller here, not the buyer.
Who owns Liquid I.V.?
Liquid I.V. is owned by Unilever, which sits it inside its Beauty and Wellbeing business group alongside Nutrafol, Paula's Choice, K18, OLLY, and SmartyPants. Unilever bought Liquid I.V. in 2020, and the brand crossed a billion dollars in retail sales under Unilever ownership in 2025. Unilever is separating its food and ice-cream businesses to become a beauty, wellbeing, and personal-care company.
Who owns Marc Jacobs?
Marc Jacobs is owned by WHP Global, the brand-management firm behind Toys R Us, Vera Wang, Anne Klein, and Bonobos. WHP Global, with G-III Apparel as a partner, acquired Marc Jacobs from LVMH in a deal reported at $850M in May 2026, and Marc Jacobs the designer stays on as creative director. WHP also holds a 50% controlling stake in Lands' End.
Who owns Salt and Stone?
Salt and Stone is majority-owned by private-equity firm Advent International, which took a majority stake in the premium body-care and deodorant brand in March 2026. Growth investor Humble Growth exited in the deal, and founder Nima Jalali retained a minority stake. Reported comparable deals implied a valuation north of $500M, though the price was not officially disclosed, so treat that figure as rumored.
How do I find out who owns a DTC brand?
Start with the brand's own site footer and terms of service, which usually name the legal parent entity, then check the parent company's brand-portfolio page and any acquisition press release. For recent deals, the acquirer's investor-relations page or a trade outlet like Retail Dive, Beauty Independent, or BevNET states the buyer and often the price. Ownership changes constantly through M&A, so a name that was independent last year may sit inside a holdco or private-equity platform now.